Something struck quite unique to me in the recent bonds raised by these oil companies. All of them cited losses if not for these bonds. They showed the receipts of bonds as normal sales. Borrowing of this money by the government as SALES. How can you do it. To top this, they have shown profits in their books and to further aggravate this they have DECLARED DIVIDENDS and the government has coolly taken this money what it gave to them in the first place. The government has borrowed money and distributed this money as dividends, when in reality they have been running losses and have asked ONGC, the scapegoat to bear the losses, as how much can the govt. bear. I have, for long, invested in ONGC as it was one decent company heading somewhere. Today, because of the government, I am forced to share my profits to not only these refining companies but to the entire nation. Just look at it this way. The government raises money from the public, thus raising its deficit. This is a long term borrowing to fund annual shortfall. First mistake funding short term losses with long term funds. Second, receiving dividends from these companies. Why are we borrowing more and receiving dividends and thus showing income in your GDP. This is wrong as you saying that raising capital is SALES. Though most of the dividends it received from this decalaratin by companies is small compared to the overall GDP, I still feel that the entry for this transaction must not be recorded in the books as dividends. There ought to be an alternative such as a book entry for the bonds received for the year and the excess or defecits charged to it rather than to the profit and loss account, where the government gets unfair benefits, (in taxation of profits and dividends received post taxation).
Well, my interest in this government seems to be falling apart for the past few months. There seems to be a lack of proper forecasting like its predecessor-the BJP. Inspite of their current shortcomings, BJP still has a few sound people which I am not seeing in this governemnt. Critical issues being held at gun point by the LEFT and failure to take the RIGHT choices, is keeping this government heading nowhere. We are lucky that this party is spending on infrastructure, else we might be in doldrums.
June 09, 2006


June 06, 2006
Vigneshwara Exports Limited - Another IPO
Well it looks like the stock markets just loves to see an IPO every week. So next in line is this company. The company is based out of Mumbai and the office is in Parel, a place where I was staying for two months. However, the place has seen tremendous appreciation of land value, but as this place is only the registered address and also since I have not seen the place I shall not comment on it. Anyways, coming to the IPO, the issue has been priced between Rs.121 and Rs.140. The IPO looks to gather around 50-60 crores from the market. Compared to the previous issues from ICICI, ONGC and possibly the DLF issue, this looks like it will hardly have any impact on the market and will comfortably sale through even the company does not advertise in the market.
This issue is not fraught without risks.
First, that comes to my mind is the promoters stake. The promoters are diluting their stake in the company to below 50%. I do not understand the reason for such a drastic step for the company.
Second, the company was into diamond trading for the past five years. Post this issue the company is planning to exit from this business. Now, that is something that needs attention. The company has entered into a field where the competition is already on the higher side creating heavy pricing issues. This should have been forecasted before entering. However, the company seems to have taken the poison pill and have decided to move from it.
Third, VEL is getting regular business from existing customers. Its top 5 clients have account for more than 75% of the business. Though this has been reducing over the past few years, this is one factor that I would be keen to looking at during the coming few quarters of the company. The company is a regular in a show in Germany for the past 15 years but it has not been able to increase its customer base for these many years. One should give this some thought.
Fourth, the company's pricing policy without using LC. As far as the customer is a regular for the company, this strategy works fine, else one would consider the risk for non-payment.
Fifth, the company's capital structure-post 2003, the company has changed the capital structure 7 times by bringing in fresh capital. However, the company has always issued the capital at extremely low cost to the promoters. Till 2005, the company issued at Rs.60 to the promoters. This was increased to Rs.100 in a month. I have no reason why things changed dramatically in a span of couple of months. The promoter will actually double his returns on his investment made last year. However, if one looks at the issue, the company has issued to the promoters at about 6-8 times earnings. Sometimes, I do wonder, if it right for the promoters to have issued the shares at such low prices when he knows that he has the option to dilute his stake when he brings his company to the public. Finally, a small irrelevant issue, the company's prospectus was mostly referring to the opportunity in US when it hardly has operations in that country. The company only has plans to enter into this market after the issue.
Positives
While we have spent our time on the negatives of the company, here's the brighter side. The company has been growing aggressively. Assets have grown by more than 14%. Inventories though has been a problem with certain years of poor forecasting, but the company has increased its sales by more than 150% in the past five years. The company has a CAPEX of 200 crores in the next few years and have lined up their capital. The company is making use of the Technology Upgradation Fund provided by the government. The rest is being funded by the IPO which is expected to raised about 55-63 crores. However, the company has sales of around 1200 crores for the past couple of years. I like the industries' prospectus with immense potential to grow.
Neutral
The company's capacity utilization has been below expectation and the bottlenecks seems to have created the problem which is being addressed with the cash inflows from the IPO. The company is increasing reliant on external supplies for its raw materials. Though this will be reduced by the IPO, this still is a concern that should be addressed by the company. The company's will be investing in heavy machinery. Hence the company should see a higher tax benefit and some security to the cash flows. The company has faced problems in dispatching within deadlines. With no cover from LC, one needs to know if there could be some risk. Power will be a concern for the company but the company seems to have addressed this issue-by hoping the government will provide with the necessary fuel.
I still am not quite clear if this company will provide the necessary appreciation that one is looking at. The cash flows which still hits me constantly is the main source of concern. However, I do hope the company will be able to manage the cash flows better. Also, the company's pricing policy at Rs.121 - Rs.140 will make it expensive today when compared to its peers. But Invest thinking of the future of the industry.
May 30, 2006
Allcargo Global IPO
Allcargo, a company that I spoke of in my previous blog. A prospectus that will make you sleep quite comfortably. To the point, I think this is yet another company that is promising more than average returns though it looks like the company has the prospects to do so.
The company is involved in logistics and has quite a history in this field. However, you will see that the company has used a few paragraphs repeatedly throughout the prospectus. In the first instance it was unnecessary as any person who is reading the first section will remember what he read and even if he does forget, a simple remark of the page would have done so. However the company insists on repeating forcing the reader to re-read. Anyways, writing a prospectus seems to be an art which ENAM is yet to master and I shall hopoefully not delve on this issue any longer.
What I liked of the company was the prospects of the industry. Again the company's will be extremely dependent on the infrastructure that the government needs to invest in. However, given the fact that considerable investment is being done by the government atleast in the improvement of ports, this company is promising to deliver something that is achievable.
The pricing is also comfortable. It recently had placed a part of the equity to outsiders at similar prices hence making the company slightly more reliable. However, the company's promoters loved to juggle their shareholding at extremely cheap prices. A share that the company's promoters should have sold for atleast Rs.350 was sold for Rs.10. Also the company has given stock options at Rs. 10 which can be exercised in the near future. However, this will not dilute the stake as it marginal in nature and would not affect the profitability when charged to the income statement.
The investment proceeds will be used for building infrastructure for the company in certain regions such as Chennai. Also, the money will be used to pre-pay debt. This is something I was not comfortable as the cost of the loan is only 11%. The company has strong cash flows and could have used that to re-pay the loan. However, this is the company's decision.
Anyways, the company has fairly valued its stock and do not know if it provides reasonable appreciation. However, when one compares to its peers, it looks there is some. Time would be the judge for this. Investing would be ideal for a period of 3 years, is my best estimate. Why 3 and not 5? Coz I am a long term investor, and prefer 3 over 5.
The company is involved in logistics and has quite a history in this field. However, you will see that the company has used a few paragraphs repeatedly throughout the prospectus. In the first instance it was unnecessary as any person who is reading the first section will remember what he read and even if he does forget, a simple remark of the page would have done so. However the company insists on repeating forcing the reader to re-read. Anyways, writing a prospectus seems to be an art which ENAM is yet to master and I shall hopoefully not delve on this issue any longer.
What I liked of the company was the prospects of the industry. Again the company's will be extremely dependent on the infrastructure that the government needs to invest in. However, given the fact that considerable investment is being done by the government atleast in the improvement of ports, this company is promising to deliver something that is achievable.
The pricing is also comfortable. It recently had placed a part of the equity to outsiders at similar prices hence making the company slightly more reliable. However, the company's promoters loved to juggle their shareholding at extremely cheap prices. A share that the company's promoters should have sold for atleast Rs.350 was sold for Rs.10. Also the company has given stock options at Rs. 10 which can be exercised in the near future. However, this will not dilute the stake as it marginal in nature and would not affect the profitability when charged to the income statement.
The investment proceeds will be used for building infrastructure for the company in certain regions such as Chennai. Also, the money will be used to pre-pay debt. This is something I was not comfortable as the cost of the loan is only 11%. The company has strong cash flows and could have used that to re-pay the loan. However, this is the company's decision.
Anyways, the company has fairly valued its stock and do not know if it provides reasonable appreciation. However, when one compares to its peers, it looks there is some. Time would be the judge for this. Investing would be ideal for a period of 3 years, is my best estimate. Why 3 and not 5? Coz I am a long term investor, and prefer 3 over 5.
Reading a Prospectus
Over the past few weeks, I have taken some fascination reading IPO prospectus'. It takes a long time as an average IPO prospectus for an equity investment has about 150-300 pages. Given the abundance free time that I seem to possess at my place, this does not seem to be a problem.
Obviously not everything is interesting and you can comfortably skip about 50-75 pages. However, the rest of the pages are interesting as they always give a wonderful picture of the company and the industry. It always tries to give you a feel that this is the company that will give you a 'ten bagger' or atleast a 'five bagger' (A 'ten bagger' is a term used for companies whose share price moves by 10 times, a term borrowed from one my gurus, Peter Lynch).
Most prospectus follow similar pattern of reading. This is extremely useful as one knows when to skip pages. I do not have any interest reading the general risk factors, endless repition of financial statements (which I shall comment upon later), statutory disclosures etc. We all understand that cigarettes are injurious to health yet it still does not prevent the smoker from enjoying his five minutes of absolute freedom.
Anyways, I enjoy reading certain specific sections of the prospectus. First, the industry - gives a wonderful picture, as always, the growth prospectus, how India is always in deficit of these basic requirements, commitments from the government (which I do not know if it will be implemented) to improve them which will be repeated from infinite number of times, outsourcing that will always happen to India and nowhere else. While it sounds pessimistic, I enjoy these statements because it tells me there is so much scope to improve in the country. Developed countries would face this biggest concern-the reason for government to spend hufe amounts of taxpayers money. India, being deficit in almost every area, has no problems. Outsourcing is a reality and cost savings are huge for companies. So, every prospectus reinforces the same issues.
The second part I enjoy reading is the company's prospects to grow in the near future. Most of them tend to be leaders in their category and almost all of them are planning to grow more than industry average. I do not know how everyone is growing at above industry average. However, this statement is something that one sees and cant help laugh at it.
The final part is the capital structure and what it intends to do with the money. This part is significant and it helps me to understand if the company is interested in building wealth to the shareholders. I like companies that repay its debt, however as far as it is above the cost of equity. As interest rates are low and most companies are 'leaders' in their industry this can't possibly happen. However, most companies seem to be expanding their capacities. Scalability will be important as companies can play with their cost structures effectively and hence gain advantage on pricing. What is most concerning is the kind of allotments the company has made in the past to its shareholders. Focus IPO for instance alloted at a steep discount to its preferential holders a year back but where charging the new investors thrice the comaparable cost. A comfortable exit option to the existing shareholders. I like reading the section that deals on civil and criminal suits against the company. Deccan Aviation tops this list. The suits against the company ran to three - four pages and it was fun reading the reports. This section is important as it shows light on the quality of management. However, the number of complaints is related to the industry, as a company that is in the end of the value chain is bound to face more. Directors of the company and their profiles is another good area of reading. Again Deccan Aviation tops in this. One of their directors is a director of 52 other companies too. If every company keeps atleast 5 board meetings a year, he will spend most of his official days just from one board room to the other. Something has to be done on this issue. You can't have directors, who are meant to safeguard shareholders interest being a director in so many companies. However this is India and as I said earlier, huge scope for improvement exists.
Finally and most importantly the current balance sheet, profit and loss and cash flow statements. This is something you will see frequently in the prospectus. Comany's projection seems to be there on every page of the prospectus, ( exaggerated but cant help myself). Yet reading this gives me an idea on whether to invest or not. Well, what I do like about these IPOs are that they do meet their projections in the near future once they are listed. As I do not track most of these companies post their issue, I do not know what has happened to their projections. My guess is that they should have met them as the stock markets seems to be quite embarrassed to list IPOs at par and most of them have done well even past a few quarters after their listing.
Currently I am reading a prospectus on Allcargo. Lemme see what fun this prospectus beholds to the reader.
Obviously not everything is interesting and you can comfortably skip about 50-75 pages. However, the rest of the pages are interesting as they always give a wonderful picture of the company and the industry. It always tries to give you a feel that this is the company that will give you a 'ten bagger' or atleast a 'five bagger' (A 'ten bagger' is a term used for companies whose share price moves by 10 times, a term borrowed from one my gurus, Peter Lynch).
Most prospectus follow similar pattern of reading. This is extremely useful as one knows when to skip pages. I do not have any interest reading the general risk factors, endless repition of financial statements (which I shall comment upon later), statutory disclosures etc. We all understand that cigarettes are injurious to health yet it still does not prevent the smoker from enjoying his five minutes of absolute freedom.
Anyways, I enjoy reading certain specific sections of the prospectus. First, the industry - gives a wonderful picture, as always, the growth prospectus, how India is always in deficit of these basic requirements, commitments from the government (which I do not know if it will be implemented) to improve them which will be repeated from infinite number of times, outsourcing that will always happen to India and nowhere else. While it sounds pessimistic, I enjoy these statements because it tells me there is so much scope to improve in the country. Developed countries would face this biggest concern-the reason for government to spend hufe amounts of taxpayers money. India, being deficit in almost every area, has no problems. Outsourcing is a reality and cost savings are huge for companies. So, every prospectus reinforces the same issues.
The second part I enjoy reading is the company's prospects to grow in the near future. Most of them tend to be leaders in their category and almost all of them are planning to grow more than industry average. I do not know how everyone is growing at above industry average. However, this statement is something that one sees and cant help laugh at it.
The final part is the capital structure and what it intends to do with the money. This part is significant and it helps me to understand if the company is interested in building wealth to the shareholders. I like companies that repay its debt, however as far as it is above the cost of equity. As interest rates are low and most companies are 'leaders' in their industry this can't possibly happen. However, most companies seem to be expanding their capacities. Scalability will be important as companies can play with their cost structures effectively and hence gain advantage on pricing. What is most concerning is the kind of allotments the company has made in the past to its shareholders. Focus IPO for instance alloted at a steep discount to its preferential holders a year back but where charging the new investors thrice the comaparable cost. A comfortable exit option to the existing shareholders. I like reading the section that deals on civil and criminal suits against the company. Deccan Aviation tops this list. The suits against the company ran to three - four pages and it was fun reading the reports. This section is important as it shows light on the quality of management. However, the number of complaints is related to the industry, as a company that is in the end of the value chain is bound to face more. Directors of the company and their profiles is another good area of reading. Again Deccan Aviation tops in this. One of their directors is a director of 52 other companies too. If every company keeps atleast 5 board meetings a year, he will spend most of his official days just from one board room to the other. Something has to be done on this issue. You can't have directors, who are meant to safeguard shareholders interest being a director in so many companies. However this is India and as I said earlier, huge scope for improvement exists.
Finally and most importantly the current balance sheet, profit and loss and cash flow statements. This is something you will see frequently in the prospectus. Comany's projection seems to be there on every page of the prospectus, ( exaggerated but cant help myself). Yet reading this gives me an idea on whether to invest or not. Well, what I do like about these IPOs are that they do meet their projections in the near future once they are listed. As I do not track most of these companies post their issue, I do not know what has happened to their projections. My guess is that they should have met them as the stock markets seems to be quite embarrassed to list IPOs at par and most of them have done well even past a few quarters after their listing.
Currently I am reading a prospectus on Allcargo. Lemme see what fun this prospectus beholds to the reader.
May 29, 2006
Prime Focus an IPO - Focus on IPO
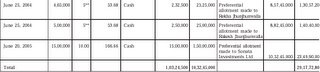
Prime Focus has come out with an IPO from May 25th -May 31, 2006. An interesting IPO coming from a sector that seems to be doing well-the entertainment sector. The company's performance has been stunning. The sales has grown by 60%-80% CAGR across three years. The PAT has shown even better performance. The company decided to price the issue at trailing PE of close to 50 on the lower side and updwards 70 on the higher side. Considering the performance and the future plans of the compny, it looks like the share price is fairly or slightly over-valued. My problem is not on the price of the issue but on this table that was in the offer document.
Prime Focus has come out with an IPO from May 25th -May 31, 2006. An interesting IPO coming from a sector that seems to be doing well-the entertainment sector. The company's performance has been stunning. The sales has grown by 60%-80% CAGR across three years. The PAT has shown even better performance. The company decided to price the issue at trailing PE of close to 50 on the lower side and updwards 70 on the higher side. Considering the performance and the future plans of the compny, it looks like the share price is fairly or slightly over-valued. My problem is not on the price of the issue but on this table that was in the offer document.
I do not know if the above image is clear or not. It shows three transactions, preferential in nature, made by the company to Rakesh and Rekha Jhunjunwala, and one company Sonata Investments. Rakesh and Rekha got the shares of the company at close to Rs.66 in June, 2004 and Sonata got the same shares at Rs.166. I have no problems on the pricing of these issues, though I am disappointed that the former two got the company at really attractive prices - a P/E of less than 17. Sonata Investments got the same shares at slightly above 17. While these two investments is reaping them enormous returns, the poor shareholder of the current issue, will be forced to wait for a long time to get the returns that these three investors are enjoying. If this is what one calls "Angel Investing" or Venture Capital Investments, then it surely looks like they robbed the company blind.
The fresh investors do not have to worry too much either. The company has a wonderful option for them. The IPO has the stablisation scheme for a period exceeding not more than 30 days. A simple scheme wherein the director has 'loaned', if I could use that word, to the book runners. They shall 'ensure' that the price does not fall below the issue for this period. So, the investor is atleast 'reasonably' assured of downside protection.
Yet, for a company that seems to have done well, atleast on paper, with strong cashflows, it seems to be a letdown on pricing. However, we are on a bull market and we have funds that invests in IPOs. Hopefully, they shall bring some upside to the stock.
May 24, 2006
And the crash....
I have always enjoyed crashes in the past. I enjoyed the stock markets around 2000 when everyone was excited seing sensex touching 6000. Balloons were flying around BSE to mark the fresh high. I loved seeing this crazy act by brokers, who are otherwise meant to be silent and unknown to the rest of the world. And then it happened, the inevitable or the truth prevailed as the Sensex crashed and it was the start of a long period of consolidation. I started investing at 3800 levels. What more exciting would it be to see the Sensex fall further to 2900 before the reversal actually start. Each time it fell, each time I would 'buy'. As a small investor, I feared that the stock markets would actually reach an all time high before I could invest my surplus money completely. This was my learning during the times it fell.
Things took a totally different turn this time around. Today I do not have surplus money to invest, I took money out of my treasure chest, close to 10% of my portfolio, which I always keep it liquid money, waiting for an excellent occasion to invest. I thought that day was last week and so I started investing in a stock that fell by 10%. It fell the next day by another 10%, I thought this was an amazing bargain and I invested further. Atleast, one thing I learnt was to always build a portfolio of stocks slowly. There is always time in this market to make money. But to my utter dismay, the crash occured on monday, and god it was one hell of a crash. I saw this stock fall by an amazing 20% in about two hours. Well, to compound this, the stock fell again the next day when most stocks were moving up. One of the "Blue-chip" ones that is beating me black and blue. But then that is life.
I tried to analyse if I made a mistake in my buying process. Not too many mistakes, but yes there were a few. The stock was pretty expensive but comparitavely cheaper than its peers. A leader in its field with business in India and outside. Well lets see what the future holds for this stock.
I have always enjoyed crashes in the past. I enjoyed the stock markets around 2000 when everyone was excited seing sensex touching 6000. Balloons were flying around BSE to mark the fresh high. I loved seeing this crazy act by brokers, who are otherwise meant to be silent and unknown to the rest of the world. And then it happened, the inevitable or the truth prevailed as the Sensex crashed and it was the start of a long period of consolidation. I started investing at 3800 levels. What more exciting would it be to see the Sensex fall further to 2900 before the reversal actually start. Each time it fell, each time I would 'buy'. As a small investor, I feared that the stock markets would actually reach an all time high before I could invest my surplus money completely. This was my learning during the times it fell.
Things took a totally different turn this time around. Today I do not have surplus money to invest, I took money out of my treasure chest, close to 10% of my portfolio, which I always keep it liquid money, waiting for an excellent occasion to invest. I thought that day was last week and so I started investing in a stock that fell by 10%. It fell the next day by another 10%, I thought this was an amazing bargain and I invested further. Atleast, one thing I learnt was to always build a portfolio of stocks slowly. There is always time in this market to make money. But to my utter dismay, the crash occured on monday, and god it was one hell of a crash. I saw this stock fall by an amazing 20% in about two hours. Well, to compound this, the stock fell again the next day when most stocks were moving up. One of the "Blue-chip" ones that is beating me black and blue. But then that is life.
I tried to analyse if I made a mistake in my buying process. Not too many mistakes, but yes there were a few. The stock was pretty expensive but comparitavely cheaper than its peers. A leader in its field with business in India and outside. Well lets see what the future holds for this stock.
March 07, 2006
Credit Ratings : Impact on Equity Markets
Crisil, ICRA, CARE etc all perform some activities that I never knew could help in understanding equity markets. Infact little is known of the help that they do to understand the pricing model for any company. So what is it that these credit agencies do that I found out recently :). While I do not know if this idea makes sense, but yet I shall publish what I think should be right.
Credit Rating Agency - A brief understanding
Assume an unknown company wants to expand its operations but it does not have the funds to do so. The company has a few options. Raise funds in the form of equity or debt. Equity is expensive but debt can help in saving taxes and can ensure that the company performs well as it is forced to service the interest and principal. Further assume that the company decides to raise debt. It faces a new problem. How can the company attract the investor who can be sitting anywhere in the country. Here is where the credit rating agency comes to rescue the company and the investor. A credit agency is a registered entity from SEBI and they help in rating companies to help investors compare companies before investing in their debt securities. Ratings are assigned on different parameters, such as type of industry, growth prospects for the industry, level of competition and most importantly the strength of the balance sheet, profit and loss and cash flow statements. Credit rating agencies assign a Sovereign rating for Government securities as there is no risk of default. The only risk will be on liquidity and this is also on the lower side. However, companies are given different ratings and they range from AAA, AA, A, BBB, BB, B, C and D. There are further + and - ratings within each category. The main aim is to clearly identify the type of risk involved with respect to each security. The investment grade restricts to a B. Anything further is purely risky for the investor. Now all of these are for debt securities, how is it going to impact the equity pricing for the company.
Little more history...
One of the popular methods used for identifying the share prices is by DCF method. A simple method of discounting future cash flows by an appropriate rate, which is normally the WACC, Weighted Average Cost of Capital. Now from where do we get the WACC. Cost of equity can be found using the CAPM.
Eq= Risk free Rate + Beta of the security * Risk Premium
All are freely interpretable and the individual who is optimistic will use lower values for most of the variables and the pessimist will tend to use higher values. The optimist wins when it is a bull market and the pessimist wins in a bear market. Anyways, this handles the equity portion.
Debt is a little easier. You just go to a credit rating agency and he can rate it for you. Normally the objective of a company is to achieve higher ratings as the cost of debt reduces. Each company strives to attain a AAA as it is the cheapest. Rating for a ten year paper can be benchmarked similar to equity.
Debt = Risk free Rate + Risk Premium (Increases for each lower grade)
Voila! you have got the company's WACC. Now we need to identify the cash flows. Again a little searching of the companies record and you will get to know the cash flows for the company. So now we have the cash flows and WACC. Divide the annual cash flows with the WACC and you have the company's price. So, how has the company pricing increase by a credit agency?
Lets take company Z. It is currently trading at Rs. 100 and there are 100 shares outstanding, market capitalisation of Rs. 10,000. Assume that the company has a debt of Rs.3000 and is in 'AA' rating paying 7% risk free rate and a risk premium of 3%. It pays an annual interest payment of Rs. 300 and gets a tax shield of 35%, Rs. 105. If there is a change of rating from AA to AAA, and the rating changes to 7% + 2% risk premium, the company will now pay Rs 270 and gets a tax shield of 94.5. The net savings is Rs. 19.5. Now our assumption is that the company shall maintain the same debt equity ratio. Assuming that it does, and you discount this 19.5/.09 we get a net savings of Rs. 216. This net savings is for the equity investor. Hence the share should appreciate by Rs.2.16 to 102.16. Ah! isn't this simple. How a credit agency can affect the price of the stock.
Crisil, ICRA, CARE etc all perform some activities that I never knew could help in understanding equity markets. Infact little is known of the help that they do to understand the pricing model for any company. So what is it that these credit agencies do that I found out recently :). While I do not know if this idea makes sense, but yet I shall publish what I think should be right.
Credit Rating Agency - A brief understanding
Assume an unknown company wants to expand its operations but it does not have the funds to do so. The company has a few options. Raise funds in the form of equity or debt. Equity is expensive but debt can help in saving taxes and can ensure that the company performs well as it is forced to service the interest and principal. Further assume that the company decides to raise debt. It faces a new problem. How can the company attract the investor who can be sitting anywhere in the country. Here is where the credit rating agency comes to rescue the company and the investor. A credit agency is a registered entity from SEBI and they help in rating companies to help investors compare companies before investing in their debt securities. Ratings are assigned on different parameters, such as type of industry, growth prospects for the industry, level of competition and most importantly the strength of the balance sheet, profit and loss and cash flow statements. Credit rating agencies assign a Sovereign rating for Government securities as there is no risk of default. The only risk will be on liquidity and this is also on the lower side. However, companies are given different ratings and they range from AAA, AA, A, BBB, BB, B, C and D. There are further + and - ratings within each category. The main aim is to clearly identify the type of risk involved with respect to each security. The investment grade restricts to a B. Anything further is purely risky for the investor. Now all of these are for debt securities, how is it going to impact the equity pricing for the company.
Little more history...
One of the popular methods used for identifying the share prices is by DCF method. A simple method of discounting future cash flows by an appropriate rate, which is normally the WACC, Weighted Average Cost of Capital. Now from where do we get the WACC. Cost of equity can be found using the CAPM.
Eq= Risk free Rate + Beta of the security * Risk Premium
All are freely interpretable and the individual who is optimistic will use lower values for most of the variables and the pessimist will tend to use higher values. The optimist wins when it is a bull market and the pessimist wins in a bear market. Anyways, this handles the equity portion.
Debt is a little easier. You just go to a credit rating agency and he can rate it for you. Normally the objective of a company is to achieve higher ratings as the cost of debt reduces. Each company strives to attain a AAA as it is the cheapest. Rating for a ten year paper can be benchmarked similar to equity.
Debt = Risk free Rate + Risk Premium (Increases for each lower grade)
Voila! you have got the company's WACC. Now we need to identify the cash flows. Again a little searching of the companies record and you will get to know the cash flows for the company. So now we have the cash flows and WACC. Divide the annual cash flows with the WACC and you have the company's price. So, how has the company pricing increase by a credit agency?
Lets take company Z. It is currently trading at Rs. 100 and there are 100 shares outstanding, market capitalisation of Rs. 10,000. Assume that the company has a debt of Rs.3000 and is in 'AA' rating paying 7% risk free rate and a risk premium of 3%. It pays an annual interest payment of Rs. 300 and gets a tax shield of 35%, Rs. 105. If there is a change of rating from AA to AAA, and the rating changes to 7% + 2% risk premium, the company will now pay Rs 270 and gets a tax shield of 94.5. The net savings is Rs. 19.5. Now our assumption is that the company shall maintain the same debt equity ratio. Assuming that it does, and you discount this 19.5/.09 we get a net savings of Rs. 216. This net savings is for the equity investor. Hence the share should appreciate by Rs.2.16 to 102.16. Ah! isn't this simple. How a credit agency can affect the price of the stock.
January 26, 2006
Recommendations...We always want quick money
A small, secret tip from the broker who has just found a gem and he wants you to invest today and that too immediately. This is as if the secret is being let out in the market and he wants you to capture the opprtunity now. We are always in a rush when it comes to investing in stock market. This is something which Warren Buffet too mentions time and again whenever he is asked for the reason behind his success. When I look at my mother when she goes and buys groceries in the market, I am surprised by her bargaining power. She fights tooth and nail to get the best price and not get cheated. What more, the shop-keeper knows that my mother keeps a close track on the price movements of her products. Only thing is that she does not stock too much to taken advantage of price movements:)
When it comes to decision making in the stock market, this talent is missing. She totally depends on the broker/father. She does not even bother to see if the company exists or not. It puzzles me too. I am no different, but probably I fare slightly better than my mother. It is nice to see her decision making process. In the first stage, she is not interested in investing in the stock market as she has no knowledge in it. A wonderful stage, where we see most of the housewives. It is better being this way than investing blindly. It takes a lot of convincing to make her first investment. A little bit of opportunity(or greed, depends on the timing), and some confidence showing the limited downside can lead to the next stage of her first investment. In this stage, she makes the investment after consulting a lot of people. You will have to give a lot of reasons, some she may understand and some she may not. She likes to hear the good things, and when the person who is advicing throws a lot of jargons, economic fundamentals (and most importantly uses words like "look at people spending money, your recent purchases etc) she becomes confident to make the investment. In this stage, she is extremely active and looks at her decision making very closely and will keep calling the broker to get the comfort of her investment. The broker is not that concerned as his work is completed.
The next stage is where we all make the mistake. If the first investment was a successful one, which the broker is ready to point out, we start thinking of the next move. We are ready to make the next investment, which the broker has been secretly telling you. This time the stake gets bigger as you have the profits of the previous investment to fall back on. It is interesting to note that, most 'un-educated investors' assume that they can beat the market, by just getting out of the market before the others do. Rarely has one seen this happen. If this investment and few subsequent ones turns out to be good, one sees the control shifted from my mother to the broker completely and this is where the RECOMMENDATIONS starts kicking in. The recommendations which was just a guiding tool, becomes the most important decision making criteria to buy or sell and the broker, the WARREN BUFFET. The biggest feature of this recommendation is that it highlights the BUY more than the SELL. This again can be attributed to our decision making process. Once a decision is done, we do not want to be proved wrong or we believe there is unlimited growth to that stock. We just want to look at newer opportunuties to capture before anyone can. It suddenly becomes a RAT RACE. We are so involved that the previous macro economic factors of the country and the industry, profitablity, ROI, ROE, P/E's, promoter holding all is thrown out of the window. All that is important now is that call from the broker and hopefully CNBC, NDTV Profit, Dalal Street covering an attractive article of your stock. The funny aspect of this is the emotional aspect. Every new high of your investment makes us even greedier and every fall is just an abberation as the lesser mortals have yet to understand your reasoning. Your broker's reassurances will make things comfortable. How helpless we all become...
My mother who was leading a simple life suddenly is in the midst of a big confusion. Having invested her savings, she sees a life with too much activity, which she never wanted in the first place and that frequent recommendations made her life so miserable that she will never lead the life she always wanted. She probably will only know when the market starts to fall....
Note: I used my mother only to make things simpler. My mother has never invested in the market and she leads a simple life that I sometimes desire. She is totally against this market, as she believes it is speculative. She is right at times....
A small, secret tip from the broker who has just found a gem and he wants you to invest today and that too immediately. This is as if the secret is being let out in the market and he wants you to capture the opprtunity now. We are always in a rush when it comes to investing in stock market. This is something which Warren Buffet too mentions time and again whenever he is asked for the reason behind his success. When I look at my mother when she goes and buys groceries in the market, I am surprised by her bargaining power. She fights tooth and nail to get the best price and not get cheated. What more, the shop-keeper knows that my mother keeps a close track on the price movements of her products. Only thing is that she does not stock too much to taken advantage of price movements:)
When it comes to decision making in the stock market, this talent is missing. She totally depends on the broker/father. She does not even bother to see if the company exists or not. It puzzles me too. I am no different, but probably I fare slightly better than my mother. It is nice to see her decision making process. In the first stage, she is not interested in investing in the stock market as she has no knowledge in it. A wonderful stage, where we see most of the housewives. It is better being this way than investing blindly. It takes a lot of convincing to make her first investment. A little bit of opportunity(or greed, depends on the timing), and some confidence showing the limited downside can lead to the next stage of her first investment. In this stage, she makes the investment after consulting a lot of people. You will have to give a lot of reasons, some she may understand and some she may not. She likes to hear the good things, and when the person who is advicing throws a lot of jargons, economic fundamentals (and most importantly uses words like "look at people spending money, your recent purchases etc) she becomes confident to make the investment. In this stage, she is extremely active and looks at her decision making very closely and will keep calling the broker to get the comfort of her investment. The broker is not that concerned as his work is completed.
The next stage is where we all make the mistake. If the first investment was a successful one, which the broker is ready to point out, we start thinking of the next move. We are ready to make the next investment, which the broker has been secretly telling you. This time the stake gets bigger as you have the profits of the previous investment to fall back on. It is interesting to note that, most 'un-educated investors' assume that they can beat the market, by just getting out of the market before the others do. Rarely has one seen this happen. If this investment and few subsequent ones turns out to be good, one sees the control shifted from my mother to the broker completely and this is where the RECOMMENDATIONS starts kicking in. The recommendations which was just a guiding tool, becomes the most important decision making criteria to buy or sell and the broker, the WARREN BUFFET. The biggest feature of this recommendation is that it highlights the BUY more than the SELL. This again can be attributed to our decision making process. Once a decision is done, we do not want to be proved wrong or we believe there is unlimited growth to that stock. We just want to look at newer opportunuties to capture before anyone can. It suddenly becomes a RAT RACE. We are so involved that the previous macro economic factors of the country and the industry, profitablity, ROI, ROE, P/E's, promoter holding all is thrown out of the window. All that is important now is that call from the broker and hopefully CNBC, NDTV Profit, Dalal Street covering an attractive article of your stock. The funny aspect of this is the emotional aspect. Every new high of your investment makes us even greedier and every fall is just an abberation as the lesser mortals have yet to understand your reasoning. Your broker's reassurances will make things comfortable. How helpless we all become...
My mother who was leading a simple life suddenly is in the midst of a big confusion. Having invested her savings, she sees a life with too much activity, which she never wanted in the first place and that frequent recommendations made her life so miserable that she will never lead the life she always wanted. She probably will only know when the market starts to fall....
Note: I used my mother only to make things simpler. My mother has never invested in the market and she leads a simple life that I sometimes desire. She is totally against this market, as she believes it is speculative. She is right at times....
January 04, 2006
Expense Ratio... Who is looking when investing
When advising people on Mutual Funds, I always saw people looking at few parameters for investing. The first was always 'Returns'. To me this is extremely important, however I found this an extremely narrow minded approach to investing. When advicing we had to specify reason for investing in a scheme. So, in my first few months, one parameter I explained was the 'Expense Ratio'. This is the ratio a fund is being charged for the services offered by the fund house to manage the fund and this does not refer to the normal 'entry or exit load' which most investors are aware of. My customers were quick to shoot this down and look at the return and which area was it investing. If they were comfortable with the idea, the investment was completed and I return happy. Over a period, I too stopped explaining and preferred to explain only if the demand needed. The sad part was after a two years, I stopped looking at it. Only after I shifted my jobs, did I start looking at it closely and I was surprised to see what was happening.
To understand this ratio you need to understand where is the money being made by a fund house. Though mutual fund is formed as a trust, the underlying objective for any mutual fund company is 'Profit'. Fund houses make money on the expense that is charged to their schemes. So, in effect the more the company has assets, the more it makes money. In India, fund houses are regulated with the amount of expenses that it can charge. It differs based on two factors:
As it is easier for higher amounts of money to be deployed with no huge additioanl costs, fund houses are given ceilings for the expense that it can charge based on the assets that it has in the scheme. The charges are
However, this situation is completely reversed in equity schemes. Fund houses can differentiate themselves with better stock picks. So here we see most fund houses charging the maximum possible expense on the fund. This is where I find it unfair to the investor. The investor pays a load for entering the fund. Over this amount, he is charged with another 2.5% charge. This makes the investor to lose 4.75% on every investment that he makes. Also, this is under the assumption that the investor is for a year. Also, the current practise to churn the portfolio for better returns by moving to different schemes further worsens the matter. Though the expense is not a one time charge, a customer who shifts his portfolio twice a year ends up losing 6.5% p.a. This is a phenomenal charge, considering the returns that he makes.
The investor is least bothered of this issue today. With equity markets flaring, he is making a lot of money. Agreed that this returns is better than most asset classes but is the customer making the most of his investment. The investor has taken a risk by entering this product and the fund houses charge a load as 'fees' to give to the broker who brokered this transaction. The broker ensures that the fund being sold is always a load fund. Sometimes, fund houses remove this load for higher amounts. On most occasions, this would never be revealed to the customer. After this the customer is not aware of the expense charged on the fund. He assumes that the poor returns is always because of the poor stock picks. For this, I shall not blame the broker. I have tried to teach this to my customers and they are rarely interested in it. Hence, we see this practise by fund houses to charge as much as possible.
In the U.S. fund houses such as Vanguard, thrive on reducing the costs for a product and pass the benefits to the customers. The bonus for the employees are based on the costs that it has saved. We hardly find such a practise in India. Even if it followed like in cash funds, it is more with a reason to accumualate more assets than anything else.
I believe that this situation can be changed. Though it would take a long time. Firstly, fund houses have to change their way of operations. Mutual funds have gathered a good momentum this time in gathering assets in the current market. However, this is comparitively low when we look at its participation in the equity market. To improve this funds have to make the fund attractive, a reduction of expense is necessary as this automatically improves the customers returns. Also, the load factor. The fund have to start lowering their load as this prevents most customers to enter a fund. NFOs with 'no load' have been successful in the past. Though the fund houses had to burn their money to pay the broker, it showed the success of such ventures.
It is difficult to implement considering the nature of the distribution. If one was to look at the long term prospects of this industry, I believe this practise has to be established.
Secondly, Fund houses regularly interacts with its customers. The mailers it sends on its products can show the expense it charges. Sadly, today except Franklin Templeton, I do not see this practise elsewhere. Repititive information on expense is bound to create some interest. Agents may not like the direction this might lead, however I believe this will be good for the industry in the long run.
However small this issue maybe for the industry, I am concerned. As an optimist, I strongly believe this product to have the potential of being the most important channel for investing our savings and I do not want to see a bad landing as it has happened a few year back.
When advising people on Mutual Funds, I always saw people looking at few parameters for investing. The first was always 'Returns'. To me this is extremely important, however I found this an extremely narrow minded approach to investing. When advicing we had to specify reason for investing in a scheme. So, in my first few months, one parameter I explained was the 'Expense Ratio'. This is the ratio a fund is being charged for the services offered by the fund house to manage the fund and this does not refer to the normal 'entry or exit load' which most investors are aware of. My customers were quick to shoot this down and look at the return and which area was it investing. If they were comfortable with the idea, the investment was completed and I return happy. Over a period, I too stopped explaining and preferred to explain only if the demand needed. The sad part was after a two years, I stopped looking at it. Only after I shifted my jobs, did I start looking at it closely and I was surprised to see what was happening.
To understand this ratio you need to understand where is the money being made by a fund house. Though mutual fund is formed as a trust, the underlying objective for any mutual fund company is 'Profit'. Fund houses make money on the expense that is charged to their schemes. So, in effect the more the company has assets, the more it makes money. In India, fund houses are regulated with the amount of expenses that it can charge. It differs based on two factors:
- Type of Product being offered
- Size of the Scheme
As it is easier for higher amounts of money to be deployed with no huge additioanl costs, fund houses are given ceilings for the expense that it can charge based on the assets that it has in the scheme. The charges are
- first 100 crores-2.5%
- the next 300 crores - 2.25%
- the next 300 crores - 2%
- the rest - 1.75%
However, this situation is completely reversed in equity schemes. Fund houses can differentiate themselves with better stock picks. So here we see most fund houses charging the maximum possible expense on the fund. This is where I find it unfair to the investor. The investor pays a load for entering the fund. Over this amount, he is charged with another 2.5% charge. This makes the investor to lose 4.75% on every investment that he makes. Also, this is under the assumption that the investor is for a year. Also, the current practise to churn the portfolio for better returns by moving to different schemes further worsens the matter. Though the expense is not a one time charge, a customer who shifts his portfolio twice a year ends up losing 6.5% p.a. This is a phenomenal charge, considering the returns that he makes.
The investor is least bothered of this issue today. With equity markets flaring, he is making a lot of money. Agreed that this returns is better than most asset classes but is the customer making the most of his investment. The investor has taken a risk by entering this product and the fund houses charge a load as 'fees' to give to the broker who brokered this transaction. The broker ensures that the fund being sold is always a load fund. Sometimes, fund houses remove this load for higher amounts. On most occasions, this would never be revealed to the customer. After this the customer is not aware of the expense charged on the fund. He assumes that the poor returns is always because of the poor stock picks. For this, I shall not blame the broker. I have tried to teach this to my customers and they are rarely interested in it. Hence, we see this practise by fund houses to charge as much as possible.
In the U.S. fund houses such as Vanguard, thrive on reducing the costs for a product and pass the benefits to the customers. The bonus for the employees are based on the costs that it has saved. We hardly find such a practise in India. Even if it followed like in cash funds, it is more with a reason to accumualate more assets than anything else.
I believe that this situation can be changed. Though it would take a long time. Firstly, fund houses have to change their way of operations. Mutual funds have gathered a good momentum this time in gathering assets in the current market. However, this is comparitively low when we look at its participation in the equity market. To improve this funds have to make the fund attractive, a reduction of expense is necessary as this automatically improves the customers returns. Also, the load factor. The fund have to start lowering their load as this prevents most customers to enter a fund. NFOs with 'no load' have been successful in the past. Though the fund houses had to burn their money to pay the broker, it showed the success of such ventures.
It is difficult to implement considering the nature of the distribution. If one was to look at the long term prospects of this industry, I believe this practise has to be established.
Secondly, Fund houses regularly interacts with its customers. The mailers it sends on its products can show the expense it charges. Sadly, today except Franklin Templeton, I do not see this practise elsewhere. Repititive information on expense is bound to create some interest. Agents may not like the direction this might lead, however I believe this will be good for the industry in the long run.
However small this issue maybe for the industry, I am concerned. As an optimist, I strongly believe this product to have the potential of being the most important channel for investing our savings and I do not want to see a bad landing as it has happened a few year back.
December 31, 2005
Equity or Debt Instruments
Before we decide which instrument to invest in, lets understand the various instruments on hand. The well known Fixed Deposit is what comes to all our minds. So, is 'the product' to invest in. Sadly, if one were to ask me, I would rate this to be the worst product. Before I explain, lets see the other products.
What is it that I look at when choosing a product.
Before we decide which instrument to invest in, lets understand the various instruments on hand. The well known Fixed Deposit is what comes to all our minds. So, is 'the product' to invest in. Sadly, if one were to ask me, I would rate this to be the worst product. Before I explain, lets see the other products.
What is it that I look at when choosing a product.
- Safety: This is something that comes to my mind instantly when I invest. While safety can be interpreted differently, to me it refers to the cushion the product gives for the risk that I am willing to take.
- Risk: This is probably the worst word to define. Risk is interpreted differently by everyone and everyone. To me it means that there is a probability of loss and I expect a compensation for it. Now different product come with different levels of risk. There are different types of risk. One when the product has a risk and one when external factors act on it to change the price of the product. For example, when BJP lost the election, the stock prices crashed across the board. This is an external risk. When prices of Infosys crashed when it came out with a disappointing earnings guidlines in 2003, it was an internal factor. Apart from this you have other types of risk like liquidity risk, default risk, credit risk etc. The point here is that there needs to be a clear quantitative value attached to these types of risk. I shall write something more on risk a little later....
- Returns: This is the residual that you get when you have clearly defined the above mentioned factors. If you are a person who looks at investment conservatively, then the risks that you take are on the lower side, hence the degree of safety is higher making expected returns to appreciate to be smaller.
Now lets look at the products that I fancy...
There are tax savers such as PPF, an excellent product considering that the interest rate is guarenteed by the government and the government is always pro-citizen. But then this product is least liquid. I will always invest in this product apart from my employers contribution in this fund. This will be a long term investment for me and it shall be a small part of my portfolio.
Post Office Savings Scheme is another product that one could invest. Though it is not guarenteed, the government would force the post office to provide higher rates of interest to promote savings. Again, there are problems with liquidity.
Reserve Bank of India Bonds: This is my another favorite instrument incase I do not want to have any risk and I want something better than Fixed Deposits. Though this investment is taxable, it still gives something better than FD's. This is a completely risk free product as it is backed by RBI and the possibility of it defaulting either interest or principal is infinitesimally small. An investment which is completely illiquid and you can not pledge this instrument. Extremely useful incase you are on higher income bracket and have completed all other safe products like house(s), precious jewellerly.
Money Market/Debt Mutual Funds: The final product and I do not prefer investing in anyother form of safe instrument for short periods of time. Here, time period is anywhere from one day to probably three years. The broad ranges of products that you get in this is simply amazing and this is probably the least understood of all products. Money can be invested in a liquid fund, incase your time horizon is less than a month and short term debt funds for less than a year and long term instruments for more than a year. It works the same way of a Fixed Deposit, except that this is not guarenteed. There is however a catch in this product and that is only for the long term debt products. As investments is made in securities the ideal time to invest in this is when economy is in recession and when it is just coming out of it. A poor product to invest when economy is in full swing.
Equity: The safe haven for investing when your time horizon is less than five years. A wonderful place and a little active participation has made me understand that this product can be invested for years and the longer that I stay the better returns that I make. To me, it is a nice feeling of owning a company and even better if I can see my wealth accumulate better than other debt products. I prefer taking risks that I can bear with and though I do not set goals when I invest in equity, I like to follow a Warren Buffet style of investing. To invest in a stock like owning and working for the company.
Equity Mutual Funds: This is another place where most of my investments will be if I am not in a position to devote a lot of my time on stocks. Also, this product is useful as the fund managers' access to information is better than as an individual. There is a problem with this though. Fund managers are tracked very closely and they tend to take calls on companies that are safer. However, I believe that this will be better than not investing in equities at all.
I shall explain my investment philosophy with every product in more detail later....
November 26, 2005
For the Illilterates...
There is a problem of blogging for the illiterates. A prime example would be me. After having taken pains on thinking of three articles, I see my 'edit posts' and see all my previous articles written. So, I thought this should be a waste of resources having copies in multiple places and do the wonderful thing of deleting it. Only when I come back later that I see that I have deleted all my articles. There comes the small but a useful and painful learning that 'never delete your posts that are still in comments'
I shall re-write the articles in the near future hopefully if I have the inspiration. In the meantime there is a lot more to discuss :)
There is a problem of blogging for the illiterates. A prime example would be me. After having taken pains on thinking of three articles, I see my 'edit posts' and see all my previous articles written. So, I thought this should be a waste of resources having copies in multiple places and do the wonderful thing of deleting it. Only when I come back later that I see that I have deleted all my articles. There comes the small but a useful and painful learning that 'never delete your posts that are still in comments'
I shall re-write the articles in the near future hopefully if I have the inspiration. In the meantime there is a lot more to discuss :)
Subscribe to:
Posts (Atom)


